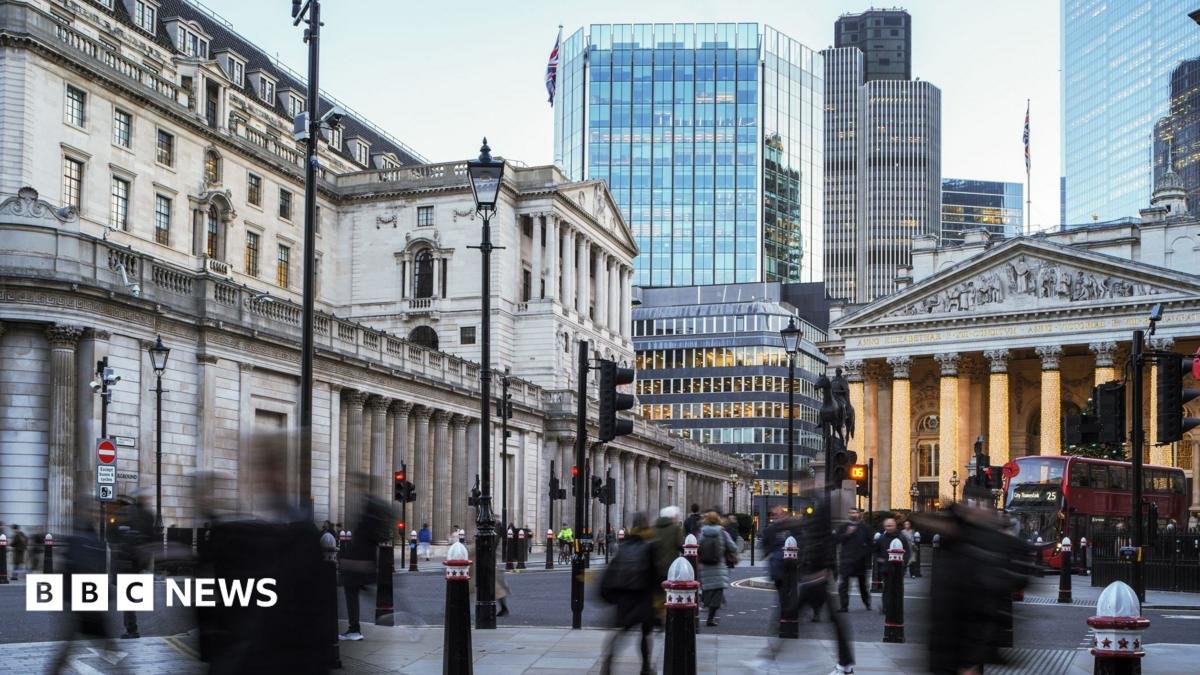
The Bank of England is poised to increase interest rates on Thursday for the first time in more than three years, marking a significant shift in monetary policy that will affect borrowers and savers across the UK.
Most analysts expect the benchmark rate to rise from 3.75% to 4%, a move that would increase borrowing costs for individuals and businesses but offer better returns for savers. The Bank's Monetary Policy Committee (MPC) has held rates steady at its last six meetings, but rising inflation, driven largely by fuel and energy costs, is expected to force its hand.
Inflation Pressures Mount
The Consumer Prices Index (CPI) measure of inflation stood at 3.5% in the year to September 2026, up from 3.1% the previous month and well above the Bank's 2% target. The ongoing impact of the Iran war, particularly on energy and fuel prices, has filtered through to the UK economy, and millions of domestic energy customers are bracing for a hefty rise in prices in January.
The Bank rate has fallen from its 2023-24 peak of 5.25%, but the recent uptick in inflation has prompted policymakers to reconsider. The announcement is scheduled for 12:00 GMT on Thursday, and close attention will be paid to any hints from the MPC on the future direction of interest rates.
"The decision is increasingly less about whether rates reach 4% and more about what follows after that," said Chris Cheverall, head of UK at trading platform CMC Markets. "A quarter-point rise is already widely expected, but the Bank now has to balance inflation that is still too high against an economy where the growth outlook has weakened sharply."
Impact on Mortgages and Savings
Were the Bank rate to rise, there would be an immediate impact on the 510,000 tracker mortgage-holders. According to calculations by banking trade body UK Finance, a 0.25 percentage point rise would mean a £31 increase in monthly repayments for someone with a typical tracker home loan. The 470,000 mortgage-holders on variable deals would need to wait for their lender's reaction, but typically a 0.25 percentage point rise would mean a £14 increase per month.
For those on fixed deals, the picture is more nuanced. While their monthly payments are not immediately affected, their future deals are, and lenders have already priced in the expected rate rise when quoting new deals. As of 4 November, the average two-year fixed residential mortgage rate was 5.96%, while the average five-year rate stood at 5.99%, according to Moneyfacts. This means anyone rolling off a five-year deal faces a much bigger mortgage bill.
Broker L&C said that average mortgage rates offered by the 10 biggest lenders suggested some borrowers now faced paying almost £5,000 more each year in repayments on a £200,000 mortgage over 25 years than those who secured a remortgage deal in 2021. Five years ago, the average five-year fixed remortgage rate among the 10 biggest lenders was 1.30%.
Relatively high fixed rates have prompted some people to consider choosing trackers, hoping the rate would be lower even if the Bank rate rises in the coming months. "The right choice ultimately depends on borrowers being confident they can stomach future rises. The devil is in the detail," said Rachel Springall from Moneyfacts.
Savers, on the other hand, could see the interest rates offered to them improve in light of any rise in the Bank rate. Lenders, as well as policymakers at the Bank of England, are having to judge what may happen to the UK's economic outlook, which is highly connected to changes in international events.