The Bank of England's decision to raise interest rates for the first time in over three years is sending ripples through the UK economy, with millions of households bracing for higher borrowing costs. The move, aimed at curbing inflation linked to the Iran war, comes as food, fuel, and energy prices continue to climb.
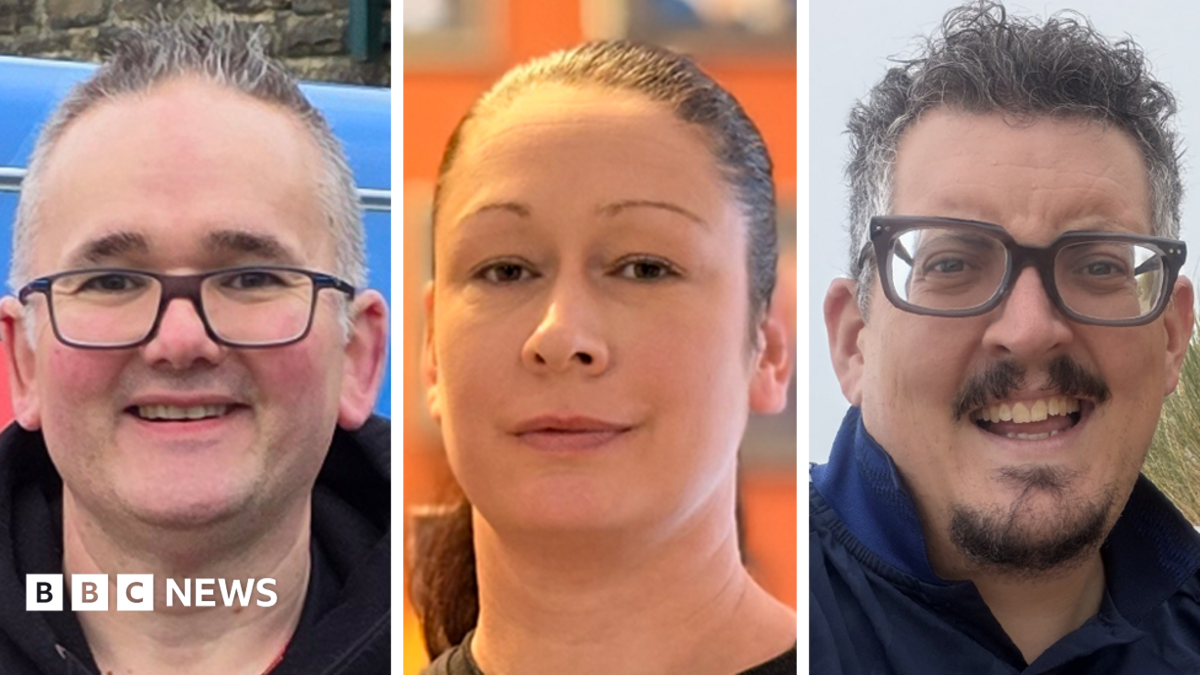
While higher rates can benefit savers, they spell trouble for borrowers. Mortgages, credit cards, and personal loans are set to become more expensive, adding financial strain for families already grappling with the cost of living crisis. The BBC spoke to three individuals about how they are being affected.
Peter Gill: 'Inflation goes up, interest rates go up, and you have even less money'
Peter Gill, 48, from Halifax, is one of the 1.3 million Britons on a variable rate mortgage. These loans track the Bank of England's base rate, so Thursday's quarter-point increase will push his monthly repayments up by about £45. He fears they could rise further but believes switching to a fixed-rate deal would be even more costly.
The father of two runs a small tiling business and has seen his costs soar. He has had to increase staff wages due to the national minimum wage rise, and raw material costs have climbed because of the conflict in Iran. At home, food, gas, and electricity bills are all higher. To shield his family, he is working 'about six and a half days a week'.
'From my point of view, inflation goes up which costs you, then interest rates go up and you have even less money,' he says.
Dawn Fazackerley-King: 'I don't know where that money is going to come from'
Most UK mortgage holders are on fixed-rate deals, but they are not immune. David Hollingworth of brokers L&C Mortgages notes that fixed rates have already risen in anticipation of higher interest rates, and many will be shocked at how much more expensive new deals are compared to five years ago.
Dawn Fazackerley-King, a Pilates instructor from near Ipswich, is about to refix her mortgage. Her current five-year fixed deal at 1.4% is ending, and the best she can find is 5.69%. That will add about £200 to her monthly payments.
'I don't know where that money is going to come from, it's something we are going to have to figure out as a family. It's stressful,' she says. She and her husband, who have a joint income of around £70,000, have already cut back on direct debits and say there is 'no more obvious fat to trim'. Both work full time, so taking on extra work is not an option.
'We're still living in the same property, our household costs are remaining the same,' she adds. 'It's an additional cost of several hundred pounds but we're not getting anything extra for that.'
Ben Thomas: 'Another cost to deal with'
Rising interest rates also affect credit card borrowing. Ben Thomas, 41, from Shropshire, retrained as a paramedic during the pandemic after a mental health crisis, but the drop in income left him relying on credit cards and personal loans. He is now £52,000 in debt.
Ben has agreed to pause interest on most of his debt, but he is still incurring charges on around £2,000 of credit card debt and worries about repayments increasing. 'With all that's going on, rising interest rates is another cost to deal with,' he says.
He and his wife pay £760 a month on their mortgage and have also struggled with higher food and energy bills. Simon Trevethick, head of communications at debt charity StepChange, which has been helping Ben, says the organisation has seen a 20% increase in people seeking support this year and warns of tougher times ahead. 'If higher borrowing costs feed through into household budgets over the coming months, we could see further pressure on people seeking support,' he says.